Analysis
One Chuan Grove 2027 Price Guide: How Much Cash and CPF Do Buyers Really Need?
One Chuan Grove is shaping up to be one of the most anticipated new condominium launches in Lorong Chuan in 2027.
With 1,056 residential units, approximately three minutes' walk to Lorong Chuan MRT, and a substantial selection of family-sized homes, the development is likely to attract interest from HDB upgraders, first-time private property buyers and families seeking larger homes.
But beyond the excitement surrounding a new launch, there is one important question every buyer should ask:
How much cash and CPF do I actually need to purchase a home at One Chuan Grove?
The answer is not as straightforward as multiplying the purchase price by 25%.
Buyers must consider the initial cash booking fee, CPF availability, Buyer's Stamp Duty (BSD), Additional Buyer's Stamp Duty (ABSD), mortgage eligibility and the progressive payment schedule during construction.
For HDB upgraders, the timing of selling their existing property can make an enormous difference to their financing requirements.
In this guide, we examine three realistic buyer scenarios to help you understand the financial commitments involved in purchasing at One Chuan Grove.
Important disclaimer: One Chuan Grove's official developer price list has not been released. This guide uses an illustrative pricing range of $2,700 to $3,200 psf for financial planning purposes only. These figures are not confirmed developer prices, launch-price indications or guaranteed starting prices.
1. One Chuan Grove 2027: How Much Might the Units Cost?
One Chuan Grove's preliminary unit mix includes homes ranging from 474 sq ft one-bedroom apartments to 1,561 sq ft five-bedroom luxury residences with private lifts.
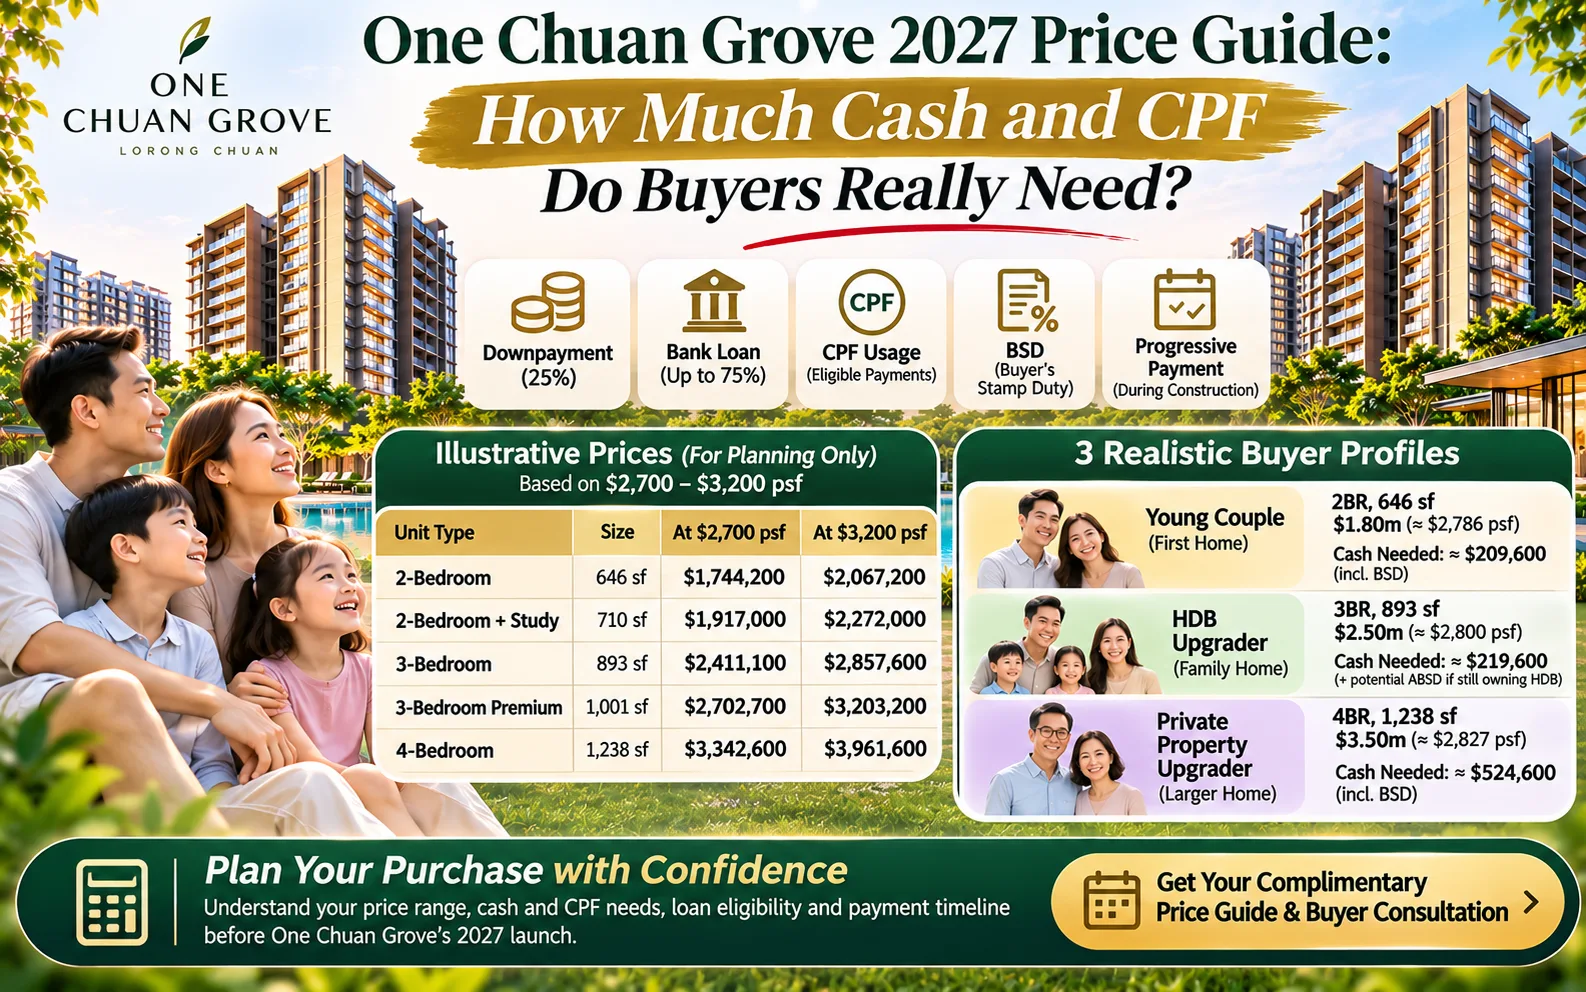
For planning purposes, we have prepared the following illustrative price matrix.
One Chuan Grove Illustrative Price Matrix ($2,700–$3,200 PSF)
Unit Type | Size | At $2,700 PSF | At $3,200 PSF |
|---|---|---|---|
1-Bedroom | 474 sf | $1,279,800 | $1,516,800 |
2-Bedroom | 581 sf | $1,568,700 | $1,859,200 |
2-Bedroom Premium | 646 sf | $1,744,200 | $2,067,200 |
2-Bedroom Premium + Study | 710 sf | $1,917,000 | $2,272,000 |
3-Bedroom | 807 sf | $2,178,900 | $2,582,400 |
3-Bedroom | 840 sf | $2,268,000 | $2,688,000 |
3-Bedroom | 893 sf | $2,411,100 | $2,857,600 |
3-Bedroom Premium / Flexi | 1,001 sf | $2,702,700 | $3,203,200 |
4-Bedroom | 1,076 sf | $2,905,200 | $3,443,200 |
4-Bedroom Premium | 1,238 sf | $3,342,600 | $3,961,600 |
4-Bedroom Luxury (Private Lift) | 1,356 sf | $3,661,200 | $4,339,200 |
5-Bedroom Luxury (Private Lift) | 1,561 sf | $4,214,700 | $4,995,200 |
Illustrative prices only. Official pricing, final unit sizes, configurations and availability remain subject to developer confirmation.
Why Purchase Quantum Matters More Than PSF Alone
A buyer comparing a 3-bedroom home at 807 sq ft with a larger 1,001 sq ft Premium or Flexi configuration should consider more than the difference in price per square foot.
The additional space may provide a more comfortable living environment, particularly for families with children or those requiring a home office.
However, a larger home also means a higher purchase quantum, additional stamp duty and a larger mortgage commitment.
For example, at an illustrative $2,800 psf:
An 807 sq ft 3-bedroom would cost approximately $2.26 million.
A 1,001 sq ft 3-bedroom Premium would cost approximately $2.80 million.
That is a difference of approximately $543,000.
The question is whether the additional space justifies the extra financial commitment for your household.
This is why I encourage buyers to begin with financial planning before deciding which unit type to pursue.
2. Understanding the Downpayment: Do You Really Need 25% Cash?
One of the most common misconceptions about buying a private condominium is that buyers must prepare 25% of the purchase price entirely in cash.
That is not necessarily correct.
For an eligible buyer obtaining a 75% bank housing loan, the typical funding structure is:
Payment Component | Percentage | Funding |
|---|---|---|
Booking fee | 5% | Cash |
Exercise of Sale & Purchase Agreement | 15% | Cash and/or eligible CPF |
Remaining equity contribution | 5% | Cash and/or eligible CPF |
Bank housing loan | 75% | Bank financing |
Total | 100% |
The 5% booking fee must generally be paid in cash.
Eligible CPF Ordinary Account savings may be used for subsequent payments, subject to CPF rules and available balances.
For a hypothetical $2.5 million purchase, the buyer's total 25% equity contribution is $625,000.
However, only $125,000 is the mandatory 5% cash booking component under the assumed 75% financing structure.
The remaining $500,000 may potentially be funded through a combination of cash and eligible CPF savings.
Buyers must also budget separately for BSD, possible ABSD, legal fees and other costs.
The key consideration is not just how much you need, but when you need it.
3. Three Realistic One Chuan Grove Buyer Profiles
Different buyers face very different financial circumstances, even when purchasing within the same development.
Let's examine three common profiles.
Buyer Profile 1: Young Couple Buying Their First Private Home
Daniel and Rachel — First-Time Homebuyers
<text_placeholder></text_placeholder>
Daniel and Rachel are both Singapore Citizens in their early thirties.
They are currently renting and planning to purchase their first property together.
They are considering a 646 sq ft two-bedroom Premium unit at One Chuan Grove.
Illustrative purchase price: $1,800,000 ($2,786 psf)
Purchase Breakdown
Item | Amount |
|---|---|
Purchase price | $1,800,000 |
5% cash booking fee | $90,000 |
15% S&P payment | $270,000 |
Remaining 5% equity | $90,000 |
Total 25% equity | $450,000 |
75% bank loan | $1,350,000 |
Buyer's Stamp Duty | $59,600 |
ABSD | $0 |
Suppose the couple has a combined CPF Ordinary Account balance of $300,000 available for the purchase.
They could potentially structure their funding as follows:
Funding Source | Amount |
|---|---|
Cash booking fee | $90,000 |
CPF towards S&P | $270,000 |
Remaining CPF towards equity | $30,000 |
Additional cash equity | $60,000 |
Total cash equity | $150,000 |
BSD, initially funded in cash | $59,600 |
Illustrative initial cash funding requirement | $209,600 |
The $209,600 represents total cash funding over the relevant initial and construction-stage milestones, not an amount entirely payable on booking day. It excludes legal fees and other costs.
Eligible CPF reimbursement of stamp duty may be possible, but buyers should not assume reimbursement is available without checking their CPF position.
How Much Would Their Mortgage Cost?
Assuming a $1.35 million loan over 30 years:
Interest Rate | Approximate Monthly Instalment |
|---|---|
2.0% | $4,990 |
2.5% | $5,335 |
3.0% | $5,690 |
4.0% | $6,445 |
These are illustrative fully disbursed loan repayments. Actual rates, tenure and loan eligibility will depend on the bank's offer and the buyers' financial circumstances.
My observation: For first-time buyers, One Chuan Grove's progressive payment structure may provide time to build additional savings during construction.
However, the couple should plan for the eventual full mortgage instalment rather than relying on the lower repayments during the early construction stages.
Buyer Profile 2: HDB Upgraders Moving Into a Three-Bedroom Home
Kelvin and Michelle — Family With Two Children
Kelvin and Michelle are Singapore Citizens in their late thirties.
They currently own a five-room HDB flat and are considering upgrading to a three-bedroom condominium.
Their priorities include remaining within a familiar neighbourhood, convenient MRT access and a comfortable home for their growing family.
They are considering an 893 sq ft three-bedroom unit at One Chuan Grove.
Illustrative purchase price: $2,500,000 ($2,800 psf)
Purchase Breakdown
Item | Amount |
|---|---|
Purchase price | $2,500,000 |
5% cash booking fee | $125,000 |
15% S&P payment | $375,000 |
Remaining 5% equity | $125,000 |
Total 25% equity | $625,000 |
75% bank loan, if eligible | $1,875,000 |
Buyer's Stamp Duty | $94,600 |
Potential ABSD if still owning HDB | $500,000 |
This is where financial planning becomes particularly important.
Should They Sell Their HDB Before Buying One Chuan Grove?
If Kelvin and Michelle sell their HDB flat before purchasing One Chuan Grove, they may be able to:
Release cash proceeds from their existing property.
Refund CPF principal and accrued interest into their CPF accounts.
Discharge their existing housing loan.
Potentially avoid ABSD on their replacement property.
Improve their eligibility for a higher LTV on the new housing loan.
However, they will need to plan their accommodation between the HDB sale and the completion of One Chuan Grove.
What Happens If They Buy First?
If they purchase One Chuan Grove while still owning their HDB flat, the new purchase may initially attract 20% ABSD.
On a $2.5 million property, this amounts to $500,000.
Eligible married couples with at least one Singapore Citizen spouse may qualify for ABSD remission or refund, subject to IRAS conditions.
For an uncompleted property, one important condition generally requires the existing residential property to be sold within six months of the new property's TOP or CSC, whichever is earlier.
Other conditions also apply.
This means that even where a future ABSD refund may be available, the couple must carefully plan how to fund the tax upfront.
An existing housing loan may also reduce the maximum LTV available for the new purchase.
Understanding Their HDB Sale Proceeds
Suppose their HDB flat is worth $1,050,000.
The couple should not assume that the entire $1.05 million becomes available for their next purchase.
The sale proceeds must first account for:
Outstanding housing loan.
CPF principal used for the HDB purchase.
CPF accrued interest.
Selling expenses and other applicable deductions.
The resulting cash proceeds and CPF refunds should be calculated separately.
CPF refunded to their Ordinary Accounts may potentially be used towards One Chuan Grove, subject to prevailing CPF rules.
How Much Would Their Mortgage Cost?
Assuming a $1.875 million loan over 30 years:
Interest Rate | Approximate Monthly Instalment |
|---|---|
2.0% | $6,930 |
2.5% | $7,410 |
3.0% | $7,905 |
4.0% | $8,952 |
My observation: For HDB upgraders, the biggest financial decision is often not which condominium to buy.
It is how to coordinate the sale of their existing HDB flat, release their CPF savings, manage ABSD exposure and secure appropriate financing.
A well-planned timeline can make the upgrade significantly more manageable.
Buyer Profile 3: Private Property Owners Upgrading to a Larger Family Home
Adrian and Sharon — Established Family Upgrading to Four Bedrooms
Adrian and Sharon are Singapore Citizens in their forties.
They currently live in a private condominium but are considering upgrading to a larger home with more space for their children.
They are attracted to One Chuan Grove's proposed family-oriented facilities and larger residential configurations.
Their preferred unit is a 1,238 sq ft four-bedroom Premium.
Illustrative purchase price: $3,500,000 ($2,827 psf)
For this example, assume their existing property has already been sold and the previous housing loan discharged before purchasing One Chuan Grove.
Purchase Breakdown
Item | Amount |
|---|---|
Purchase price | $3,500,000 |
5% cash booking fee | $175,000 |
15% S&P payment | $525,000 |
Remaining 5% equity | $175,000 |
Total 25% equity | $875,000 |
75% bank loan, if eligible | $2,625,000 |
Buyer's Stamp Duty | $149,600 |
ABSD, assuming no other property | $0 |
Suppose the couple has $500,000 in eligible CPF OA savings after selling their existing property.
Their funding structure could look like this:
Funding Source | Amount |
|---|---|
Total equity contribution | $875,000 |
CPF OA utilised | $500,000 |
Cash equity required | $375,000 |
BSD | $149,600 |
Total cash funding requirement | $524,600 |
This assumes BSD is initially funded in cash, and excludes legal fees and other expenses.
How Much Would Their Mortgage Cost?
Assuming a $2.625 million loan over 30 years:
Interest Rate | Approximate Monthly Instalment |
|---|---|
2.0% | $9,700 |
2.5% | $10,370 |
3.0% | $11,070 |
4.0% | $12,532 |
There is an important qualification for buyers in their forties.
A 30-year loan may extend beyond the applicable age threshold for maximum LTV eligibility.
If the loan tenure exceeds 30 years or extends beyond age 65, the maximum LTV for an individual borrower may be reduced, depending on the number of outstanding housing loans and other regulatory conditions.
A lower LTV would mean a higher required downpayment.
For example, if the couple qualifies for only 55% financing instead of 75%, the required equity contribution on a $3.5 million property would increase from $875,000 to $1,575,000.
That is an additional $700,000 to be funded through eligible cash and CPF, with applicable minimum cash requirements.
My observation: Buyers upgrading to larger homes should not automatically maximise their borrowing capacity.
The purchase should remain sustainable alongside retirement planning, children's education expenses and other financial commitments.
4. Comparing the Three Buyer Profiles
The following table summarises the illustrative purchase requirements.
First-Time Buyers | HDB Upgraders | Private Property Upgraders | |
|---|---|---|---|
Unit type | 2BR, 646 sf | 3BR, 893 sf | 4BR, 1,238 sf |
Purchase price | $1.80m | $2.50m | $3.50m |
Approx. PSF | $2,786 | $2,800 | $2,827 |
5% booking cash | $90,000 | $125,000 | $175,000 |
Total 25% equity | $450,000 | $625,000 | $875,000 |
BSD | $59,600 | $94,600 | $149,600 |
Potential ABSD | $0 | $500,000 if HDB retained | $0 if no other property |
75% loan, if eligible | $1.35m | $1.875m | $2.625m |
Monthly instalment at 3%, 30 years | ~$5,690 | ~$7,905 | ~$11,070 |
All scenarios assume Singapore Citizen buyers, eligibility for the stated loan amounts, and the illustrative ownership circumstances described.
The actual amount of cash needed will depend on CPF balances, outstanding loans, stamp duty obligations, age and loan tenure.
5. How Much Buyer's Stamp Duty Will One Chuan Grove Buyers Pay?
Buyer's Stamp Duty is payable on residential property purchases in Singapore.
It is calculated progressively based on the higher of the purchase price or market value.
The prevailing residential BSD rates are:
Purchase Price Band | BSD Rate |
|---|---|
First $180,000 | 1% |
Next $180,000 | 2% |
Next $640,000 | 3% |
Next $500,000 | 4% |
Next $1.5 million | 5% |
Amount exceeding $3 million | 6% |
For quick reference:
Illustrative Purchase Price | BSD |
|---|---|
$1,600,000 | $49,600 |
$1,800,000 | $59,600 |
$2,000,000 | $69,600 |
$2,500,000 | $94,600 |
$3,000,000 | $119,600 |
$3,500,000 | $149,600 |
$4,000,000 | $179,600 |
$5,000,000 | $239,600 |
BSD must be accounted for separately from the property's downpayment.
Eligible CPF savings may be used for stamp duty, but buyers should confirm the applicable payment and reimbursement procedures before committing to a purchase.
6. Can CPF Be Used to Buy One Chuan Grove?
Yes.
Eligible CPF Ordinary Account savings can generally be used towards purchasing a private residential property in Singapore.
This includes:
Downpayment: CPF can potentially fund part of the purchase price after the mandatory cash booking component.
Stamp duty and legal fees: Eligible expenses may be paid or reimbursed using CPF, subject to CPF procedures.
Progressive payments: CPF may be used for eligible construction-stage payments.
Monthly mortgage instalments: CPF OA savings may be used to service the housing loan, subject to applicable limits.
However, CPF usage is not unlimited.
The amount available depends on the buyer's existing CPF balance, prior property usage, applicable withdrawal limits, remaining property lease and retirement-related requirements.
For buyers who have already used CPF to purchase another property, additional restrictions may apply.
CPF Refunds When Selling Your Existing Property
When an existing property purchased using CPF is sold, the CPF principal withdrawn and accrued interest generally must be refunded to the owner's CPF account, subject to applicable rules.
These refunded savings may potentially be reused for another eligible property purchase.
However, buyers should distinguish between:
Cash proceeds: Money received after settling the housing loan, CPF refund and other sale-related expenses.
CPF refund: Money returned to the owner's CPF account, which remains subject to CPF usage rules.
A family upgrading from an HDB flat may have substantial housing equity but relatively limited immediate cash proceeds.
Understanding this distinction early is essential.
7. One Chuan Grove Progressive Payment Schedule Explained
One of the important financial features of purchasing a new-launch condominium is the progressive payment schedule.
Instead of paying the entire purchase price within a short period, payments are linked to construction milestones.
For illustration, consider a $2.5 million One Chuan Grove unit.
The following is a typical simplified schedule for a building-under-construction private residential purchase.
Construction Stage | Payment | Amount | Cumulative |
|---|---|---|---|
Booking / Option to Purchase | 5% | $125,000 | 5% |
Sale & Purchase Agreement | 15% | $375,000 | 20% |
Foundation completed | 10% | $250,000 | 30% |
Reinforced concrete framework | 10% | $250,000 | 40% |
Partition walls | 5% | $125,000 | 45% |
Roofing / ceiling | 5% | $125,000 | 50% |
Doors, windows and services | 5% | $125,000 | 55% |
Car parks, roads and drains | 5% | $125,000 | 60% |
Temporary Occupation Permit | 25% | $625,000 | 85% |
Certificate of Statutory Completion | 15% | $375,000 | 100% |
Total | 100% | $2,500,000 |
The exact schedule, milestone definitions and timing will depend on the developer's prescribed Sale & Purchase Agreement.
Why This Matters to Buyers
Under an illustrative 75% loan structure, the buyer contributes the required 25% equity through cash and eligible CPF savings.
The bank then progressively disburses the housing loan as the relevant construction milestones become payable.
This means that the full mortgage is not normally drawn down immediately after booking.
During the early construction stages, monthly repayments may be substantially lower than the instalments on the fully disbursed loan.
However, the loan balance and repayment obligations increase as construction progresses.
The correct way to assess affordability is to plan for the full mortgage commitment, not just the lower repayments during construction.
8. How Much Income Do You Need to Buy One Chuan Grove?
Before committing to a purchase, buyers should obtain an In-Principle Approval from a bank.
The bank will assess income, existing debts, credit standing, loan tenure and other factors.
Total Debt Servicing Ratio (TDSR)
Singapore's prevailing TDSR framework generally limits total monthly debt repayments to 55% of gross monthly income.
This includes housing loans and other qualifying debt obligations.
Loan-to-Value Ratio (LTV)
Eligible borrowers with no outstanding housing loans may qualify for a maximum LTV of 75%.
However, the maximum LTV may be lower for buyers with existing housing loans, longer loan tenures or loans extending beyond the applicable age threshold.
Illustrative Income Requirements
Using a 4% interest rate over 30 years for simplified affordability assessment:
Housing Loan | Monthly Repayment at 4% | Approx. Minimum Gross Monthly Income |
|---|---|---|
$1,350,000 | $6,445 | $11,720 |
$1,875,000 | $8,952 | $16,280 |
$2,625,000 | $12,532 | $22,790 |
These figures assume no other monthly debt obligations and full recognition of the borrowers' incomes.
They are not guarantees of loan approval.
Self-employed buyers, commission earners and borrowers with variable income may be subject to additional income assessment adjustments.
Buyers should obtain a bank assessment before relying on any assumed loan amount.
9. Should HDB Upgraders Sell Before or After Buying One Chuan Grove?
This is one of the most important decisions for families planning to upgrade.
Option A: Sell the HDB First
Selling first can help release cash proceeds and CPF savings, discharge the existing housing loan and potentially avoid second-property ABSD.
It may also improve the buyer's ability to qualify for a higher LTV.
However, the family will need to plan accommodation while waiting for One Chuan Grove to be completed.
Option B: Buy One Chuan Grove First
Buying first may allow the family to continue living in their existing HDB flat throughout construction.
However, this approach can involve ABSD, more restrictive financing and a significantly higher initial liquidity requirement.
Eligible married couples may qualify for ABSD remission or refund if the relevant conditions are satisfied.
The appropriate strategy depends on the family's current mortgage, HDB sale proceeds, CPF savings, cash reserves and intended moving timeline.
There is no universally correct sequence.
The objective is to coordinate the property sale, financing and new purchase so that the family can upgrade without unnecessary financial pressure.
10. The Financial Mistake I Encourage Buyers to Avoid
Many buyers begin their property search by asking:
“What is the maximum property price the bank will allow me to buy?”
I believe a more useful question is:
“What is the right property price for my family's financial position and long-term plans?”
There is a difference between qualifying for a housing loan and being comfortable servicing that loan over the next 20 to 30 years.
For example, a family may qualify for a $2 million mortgage but prefer to borrow only $1.5 million.
That decision may provide greater flexibility for children's education, retirement savings, investments or unexpected household expenses.
Similarly, a family may have sufficient CPF savings to fund the downpayment but insufficient immediate cash to manage stamp duties or a temporary ABSD obligation.
A sustainable property purchase should balance:
Monthly mortgage affordability.
Available cash and CPF.
Existing property equity and sale proceeds.
Stamp duty and transaction costs.
Long-term family financial commitments.
Emergency liquidity and retirement planning.
Buying the right property is important. Buying it with the right financial structure is equally important.
11. Preparing for One Chuan Grove's 2027 Launch
One Chuan Grove is targeting a preview in February 2027, subject to developer confirmation.
With official prices not yet released, buyers can use this period to establish a realistic financial plan.
I recommend preparing three key figures before selecting your preferred unit.
Your Comfortable Purchase Budget
Determine a purchase price that allows your family to maintain a sustainable monthly mortgage commitment.
Your Available Cash and CPF
Calculate the cash booking fee, CPF available for the purchase, BSD and any potential ABSD.
For existing homeowners, include an estimate of cash sale proceeds and CPF refunds.
Your Loan Eligibility
Obtain a preliminary financing assessment based on your income, age, outstanding loans and preferred loan tenure.
Once these figures are established, you can evaluate the various One Chuan Grove layouts and price points more confidently.
12. Get Your Complimentary One Chuan Grove Price Guide and Private Buyer Consultation
As the ERA One Chuan Grove Project Division Director and an Asset Progression Strategist, my role goes beyond introducing buyers to a new condominium.
I work with clients to understand their current property position, financial resources and longer-term objectives before recommending a suitable purchase strategy.
Whether you are buying your first private property, upgrading from an HDB flat or moving into a larger family home, we can work through the numbers together.
During a complimentary 15-minute private Zoom consultation, we can discuss:
Illustrative One Chuan Grove prices for your preferred unit types.
How much cash and CPF you may need.
BSD and potential ABSD obligations.
Bank loan eligibility and estimated monthly repayments.
Progressive payment requirements during construction.
Your HDB or private property upgrading timeline.
The objective is simple: to help you determine whether One Chuan Grove is suitable for your family before you commit to a purchase.
Request your complimentary One Chuan Grove Price Guide or arrange a private 15-minute Zoom consultation.
Christopher Ng
ERA One Chuan Grove Project Division Director
Asset Progression Strategist
Website: www.onechuangrove.net
WhatsApp: 88682289
Direct consultation: https://wa.me/6588682289
Disclaimer: All prices, psf assumptions, buyer profiles, mortgage rates, payment schedules and financial illustrations are hypothetical and provided for general educational purposes. One Chuan Grove's official developer prices have not been released. Actual financing, CPF usage, BSD, ABSD and loan eligibility depend on prevailing regulations and individual circumstances. Buyers should confirm their position with their bank, CPF Board, IRAS and conveyancing lawyer before making a purchase.
Come home to One Chuan Grove with Christopher Ng 88682289
Frequently asked questions
1\. How much will One Chuan Grove cost in 2027?
One Chuan Grove's official developer price list has not been released. For financial planning purposes, an illustrative range of $2,700 to $3,200 psf is used in this guide. Based on this assumption, a 646 sq ft two-bedroom unit could cost approximately $1.74 million to $2.07 million, while an 893 sq ft three-bedroom unit could cost approximately $2.41 million to $2.86 million. These are illustrative calculations, not confirmed launch prices or developer quotations.
2\. How much cash do I need to book a unit at One Chuan Grove?
For a typical new-launch condominium purchase, the booking fee is 5% of the purchase price, payable in cash. For example: - $1.8 million property: $90,000 cash. - $2.5 million property: $125,000 cash. - $3.5 million property: $175,000 cash. Additional cash or eligible CPF savings will be required for subsequent payments, stamp duties and other purchase expenses.
3\. Can I use CPF to pay for One Chuan Grove?
Yes. Eligible CPF Ordinary Account savings can generally be used for the downpayment after the mandatory cash component, eligible stamp duties and legal fees, progressive construction payments and monthly mortgage instalments. However, CPF usage is subject to prevailing withdrawal limits, property eligibility, available CPF balances and applicable retirement-related requirements. The initial 5% booking fee must generally be paid in cash.
4\. How much downpayment is required for One Chuan Grove?
For an eligible buyer obtaining a 75% bank housing loan, the total downpayment is 25% of the purchase price. This typically comprises: - 5% cash booking fee. - 15% payable upon exercising the Sale & Purchase Agreement, using cash and/or eligible CPF. - 5% remaining equity contribution, payable at a subsequent construction milestone using cash and/or eligible CPF. For a $2.5 million property, the total 25% equity contribution is $625,000. The actual downpayment may be higher if the buyer qualifies for a lower loan-to-value ratio.
5\. How much Buyer's Stamp Duty (BSD) must I pay for One Chuan Grove?
BSD is calculated progressively based on the higher of the property's purchase price or market value. For illustration: Purchase Price | Buyer's Stamp Duty | --- | --- | $1,800,000 | $59,600 | $2,000,000 | $69,600 | $2,500,000 | $94,600 | $3,000,000 | $119,600 | $3,500,000 | $149,600 | $4,000,000 | $179,600 | BSD is payable in addition to the property downpayment. Eligible CPF savings may be used for BSD, subject to CPF procedures.
6\. Do I need to pay Additional Buyer's Stamp Duty (ABSD) when buying One Chuan Grove?
ABSD depends on the buyer's citizenship, Singapore Permanent Resident status and number of residential properties owned. Under prevailing rates, a Singapore Citizen buying a first residential property generally pays no ABSD. A Singapore Citizen purchasing a second residential property generally incurs 20% ABSD, while a third or subsequent residential property generally attracts 30% ABSD. For example, a Singapore Citizen purchasing a $2.5 million second residential property may incur $500,000 in ABSD. Certain buyers may qualify for remission or refund, subject to IRAS conditions.
7\. Can I buy One Chuan Grove before selling my HDB flat?
Potentially, yes, subject to HDB eligibility rules, including the applicable Minimum Occupation Period, and financing requirements. However, buying One Chuan Grove while retaining an existing HDB flat may trigger ABSD and reduce the maximum housing loan available. Eligible married couples may qualify for ABSD remission or refund if they satisfy the relevant conditions, including the prescribed timeline for selling their existing residential property. Buyers should review their HDB eligibility, ABSD exposure, CPF availability and financing position before deciding whether to sell first or buy first.
8\. Can I get an ABSD refund after selling my existing property?
Eligible married couples with at least one Singapore Citizen spouse may qualify for ABSD remission or refund when purchasing a replacement residential property jointly, subject to IRAS requirements. For an uncompleted property, a key condition generally requires the existing residential property to be sold within six months of the new property's TOP or CSC, whichever is earlier. Other conditions apply, including ownership and timing requirements. ABSD may still need to be funded upfront before a refund is obtained.
9\. How does One Chuan Grove's progressive payment schedule work?
One Chuan Grove is expected to follow the standard progressive payment structure applicable to building-under-construction private residential developments. Buyers generally pay 5% upon booking and 15% when exercising the Sale & Purchase Agreement. Subsequent payments are linked to construction milestones, such as foundation completion, structural works, roofing, installation works, TOP and CSC. The bank housing loan is progressively disbursed as eligible payments become due. The exact payment schedule and timing will be governed by the developer's Sale & Purchase Agreement.
10\. Do I need to start paying my full mortgage immediately after booking One Chuan Grove?
No. For a typical new-launch purchase under a progressive payment arrangement, the bank housing loan is disbursed in stages as construction progresses. Monthly mortgage repayments generally increase as more of the loan is drawn down. However, buyers should assess affordability based on the eventual fully disbursed mortgage, rather than only the lower repayments during the early construction stages.
11\. How much salary do I need to buy One Chuan Grove?
The required income depends on the purchase price, loan amount, tenure, existing debts and bank assessment. Under Singapore's Total Debt Servicing Ratio framework, total monthly debt obligations generally cannot exceed 55% of gross monthly income. For illustration, assuming a 30-year loan assessed at 4% interest and no other debts: Housing Loan | Approx. Gross Monthly Income Required | --- | --- | $1.35 million | $11,720 | $1.875 million | $16,280 | $2.625 million | $22,790 | These are simplified illustrations, not bank approval thresholds for every borrower. Actual loan eligibility depends on the bank's assessment and applicable regulatory requirements.
12\. Can self-employed buyers qualify for a One Chuan Grove housing loan?
Yes. Self-employed individuals, business owners and commission-based professionals can apply for housing loans. However, banks may assess their income differently from salaried employees, including applying adjustments to variable income and reviewing supporting financial documents. Self-employed buyers should obtain an In-Principle Approval before committing to a purchase.
13\. Is it better to sell my existing property before buying One Chuan Grove?
Selling first may help release cash proceeds and CPF savings, discharge an existing mortgage, improve financing eligibility and potentially avoid ABSD. Buying first may offer greater housing continuity but could require significantly more upfront liquidity. The better strategy depends on your existing property value, outstanding loan, CPF refunds, available cash, ABSD position and preferred moving timeline.
14\. What is the minimum cash and CPF needed for a three-bedroom unit at One Chuan Grove?
Using an illustrative purchase price of $2.5 million for an 893 sq ft three-bedroom unit, an eligible buyer obtaining 75% financing would require: - $125,000 mandatory cash booking fee. - $500,000 additional equity contribution using cash and/or eligible CPF. - $94,600 Buyer's Stamp Duty. - Additional funds for legal fees and any applicable ABSD. The total cash requirement depends on the buyer's available CPF savings and financing eligibility.
15\. When will One Chuan Grove's official price list be released?
One Chuan Grove is targeting a preview in February 2027, subject to developer confirmation. The official price list and unit-specific pricing have not yet been announced. Prospective buyers can begin reviewing their financing eligibility and preferred unit configurations before the official prices are available.
16\. How can I obtain a personalised One Chuan Grove cash and CPF calculation?
Prospective buyers can arrange a complimentary 15-minute private Zoom consultation with Christopher Ng, ERA One Chuan Grove Project Division Director and Asset Progression Strategist. The consultation can cover your preferred unit type, illustrative purchase price, cash downpayment, available CPF savings, stamp duties, estimated mortgage repayments and upgrading timeline. WhatsApp Christopher Ng: 88682289 Website: [www.onechuangrove.net](http://www.onechuangrove.net/) \*Disclaimer: All pricing and financial examples are illust